Riding a motorcycle through Alberta is a fun road trip to enjoy open roads and the ever-changing landscape. However, there are also financial implications to all rides. By having a suitable insurance policy to have in place in the event of an accident or an unexpected loss, those worries can be minimized.
In Alberta, motorcyclists must have insurance on their bikes to ride legally on the road. With basic auto insurance, coverage for third parties and accident benefits are included. Additional coverage, like collision and comprehensive, can offer further motorcycle coverage.
This is more than the legal requirement for Alberta riders, as the right policy is one that takes care of them.
Understanding Liability Protection
Third-party liability is one of the most crucial components of motorcycle insurance coverage. A rider’s liability coverage can help cover costs that are eligible if the rider causes the accident resulting in injury or property damage to another person.
At this time basic third-party insurance is mandatory in Alberta. The provincial minimums determined by the Insurance Bureau of Canada are $200,000. Even with this coverage, though, riders may want to ask themselves if a higher liability limit is a better choice for them, depending on their situation and possibly the amount of exposure they face.
This can make for a more economical sense when driving in high-traffic urban areas or over longer distances.
There are several ways to protect the motorcycle itself.
The liability coverage is mainly for the responsibility you have to others. That does not automatically cover damage to the motorcyclist’s bike.
Eligible damage caused by a collision may be covered by collision coverage. Some other risks that are not collisions, such as theft or other covered events, can be covered under comprehensive coverage. The protections available and conditions under which they are available depend on the policy.
The difference is important because motorbikes can be a big investment. If you’re ordering custom parts and accessories, they’ll need to be taken into account as well.
The policy should be consistent with the rider.
There are a number of factors which insurance rates may be influenced by. Examples of these would be the type of motorbike, the size of the engine, where he or she rode, and what type of coverage he or she selected. The deductible may also impact the premium.
Therefore, a policy must reflect the actual use of the motorcycles. A commuter who is riding regularly could have different needs than the rider who rides primarily under favorable conditions.
It is also important to be open and honest about usage and motorcycle specifics. A claim is based on the information that appears correct, and the circumstances are not disclosed, which may cause problems.
Enjoy a safer and more enjoyable ride with these tips.
The only thing that a motorcycle insurance policy can do is to cover the costs of a motorcycle accident. It can, however, minimize the financial stress that occurs after a sudden event. Riders can make informed decisions when they understand the limitations of liability, optional protection deductibles, exclusions, and policy conditions.
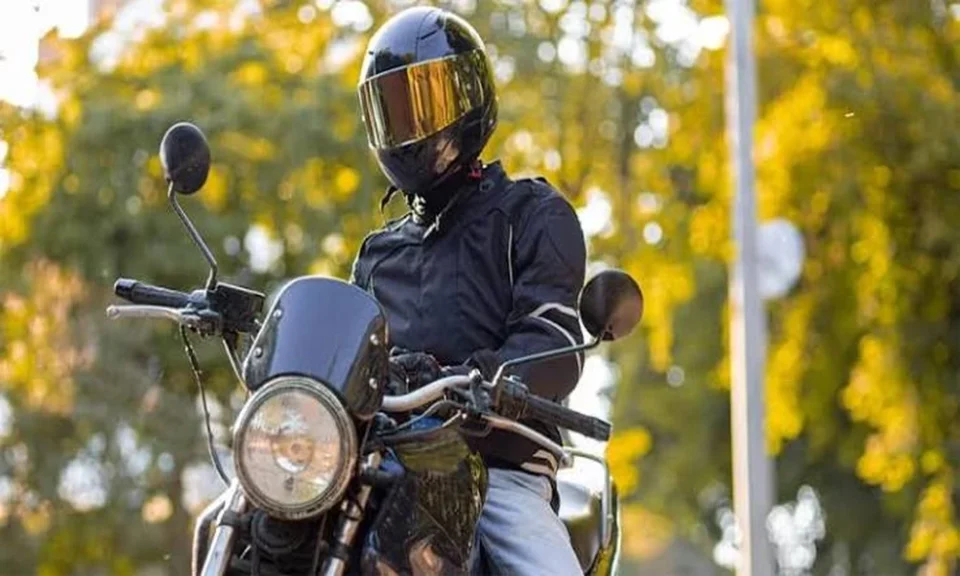
Insurance can make Alberta rides significantly easier if used in combination with proper riding behavior and protective gear and regular policy reviews. Alberta’s safe riding tips also say helmets and motorcycling protective gear are key components in safer motorcycling.